
A statement of retained earnings shows how a corporation’s accumulated profit changed during a reporting period. For Canadian owners, it connects current profit, dividends, and the equity balance carried forward. It also explains why profitable companies can show weak accumulated equity after large distributions.
| Key point | What it means |
|---|---|
| Main purpose | Reconciles the opening accumulated-profit balance with the closing balance |
| Reporting period | Usually a month, quarter, or fiscal year |
| Basic calculation | Opening balance + net income − dividends ± adjustments |
| Balance sheet link | The closing amount forms part of shareholders’ equity |
| Canadian tax link | CRA GIFI uses specific opening, income, dividend, adjustment, and ending codes |
| Main users | Owners, accountants, lenders, investors, and tax preparers |
Short answer: This equity report begins with the opening accumulated-profit balance. It adds current net income or subtracts a current loss. Then it subtracts dividends and records relevant adjustments before reaching the closing equity balance. That closing figure should agree with shareholders’ equity on the balance sheet.
Key takeaways
- The report explains movement in accumulated corporate profit, not cash available in the bank.
- Net income increases the balance, while losses and dividends generally reduce it.
- Federal corporate rules allow a statement of changes in equity or a retained earnings statement.
- CRA GIFI reporting has specific opening, income, dividend, adjustment, and ending codes.
- Private companies may present the information separately or within a broader equity statement.
What a Statement of Retained Earnings Shows
The report tracks profits a corporation keeps instead of distributing them to shareholders. It covers a period, such as a month, quarter, or fiscal year. The ending figure becomes part of shareholders’ equity on the balance sheet. There is more on this in fiscal year in Canada.
Think of the report as a bridge between profit and equity. Your income statement produces current net income, while dividend decisions affect what remains in the company. The closing equity balance then carries forward into the next reporting period.
The Business Development Bank of Canada’s guidance describes this report as tracking a company’s accumulated earnings. Its guidance also notes that some companies present the information within another financial statement. That flexibility matters because presentation can differ across reporting frameworks.
How to Calculate a Statement of Retained Earnings
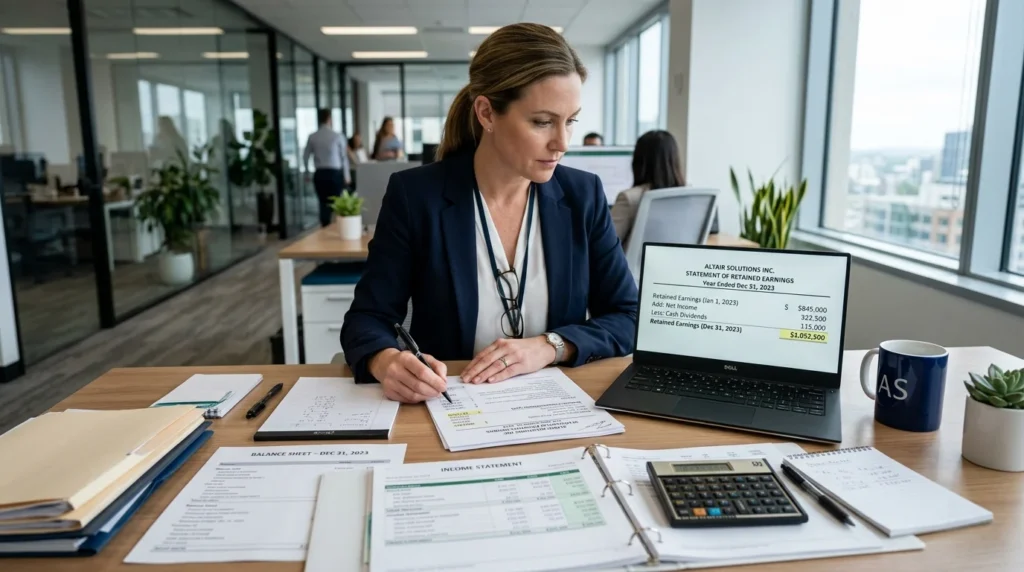
The basic calculation is simple, but the source numbers must reconcile. Use the prior period’s closing balance as the new opening balance. Then add current profit, subtract distributions, and include valid adjustments.
Ending balance = Opening balance + Net income − Dividends ± Adjustments
If the company reports a net loss, subtract that loss instead of adding income. Dividends are equity distributions, not operating expenses on the income statement. Prior-period adjustments should appear separately when they legitimately affect opening equity.
The opening number should always connect to the previous period’s closing figure. Net income should also agree with the final profit shown on the income statement. Any unexplained difference deserves investigation before finalizing the reports.
Canadian Reporting Rules and CRA GIFI Codes
For federally incorporated companies, the Canada Business Corporations Regulations set minimum annual statement contents. Section 72 permits either a statement of changes in equity or a statement of retained earnings. The financial statements also include position, income, and cash-flow reporting.
The CRA’s General Index of Financial Information maps these amounts for corporate tax filings. Code 3660 records the opening retained earnings or deficit, while 3680 records net income or loss. Code 3700 covers dividends declared, and 3849 records the ending amount.
| CRA GIFI code | Purpose |
|---|---|
| 3600 | Balance-sheet accumulated profit or deficit amount |
| 3660 | Opening balance |
| 3680 | Net income or loss |
| 3700 | Dividends declared |
| 3720 | Prior-period adjustments |
| 3740 | Other items affecting the balance |
| 3849 | Ending balance |
The ending amount should agree with the related shareholder-equity figure when reported. CRA also provides codes for prior-period and other qualifying adjustments. This makes tax mapping more detailed than the basic classroom formula.
A Worked Canadian Example
Consider Northern Trail Services Inc., a fictional Ontario corporation. It starts 2026 with an accumulated profit balance of CAD 85,000. During the year, it earns CAD 42,000 and declares CAD 12,000 in dividends.
| Calculation | Amount |
|---|---|
| Opening accumulated balance | CAD 85,000 |
| Add: Net income | CAD 42,000 |
| Less: Dividends declared | CAD 12,000 |
| Closing accumulated balance | CAD 115,000 |
The closing balance is CAD 115,000. That amount should agree with the related shareholder-equity figure on the year-end balance sheet. If it does not, review postings, dividend entries, and adjustments before finalizing the statements.
That reconciliation also shows why accurate bookkeeping matters. Bizverra’s general ledger example shows how transactions reach the trial balance before statements are prepared. Its income statement example shows where the current-year profit comes from.
How the Report Connects to Other Financial Statements
Each financial statement answers a different question. The income statement explains profitability across a period, while the balance sheet shows financial position on one date. This equity report explains how profits and distributions changed the owners’ accumulated stake.
| Statement | Main question | Connection |
|---|---|---|
| Income statement | Did the company make a profit? | Supplies current net income or loss |
| Equity movement report | Why did accumulated equity change? | Reconciles opening and closing balances |
| Balance sheet | What does the company own and owe? | Carries the closing equity amount |
| Cash-flow statement | Where did cash enter and leave? | Explains cash movement, not accumulated profit |
Do not confuse accumulated profit with cash. A company can keep profits while spending cash on equipment, inventory, or debt repayment. Owners should therefore read this report beside the balance sheet and cash-flow statement.
Period selection also affects comparison. Bizverra’s fiscal year guide explains how Canadian businesses choose and use reporting year-ends. Keep comparative periods consistent when reviewing trends across several years.
What Changes the Accumulated Balance?
Four categories usually explain movement from opening to closing equity. Profit raises the balance, while a loss lowers it. Distributions and certain accounting adjustments can also change the figure.
- Net income: Adds current-period profit.
- Net loss: Reduces accumulated corporate profit.
- Dividends declared: Reduce the amount remaining for shareholders collectively.
- Prior-period adjustments: Correct qualifying items affecting earlier periods.
- Other equity adjustments: May apply when the accounting framework requires them.
A large closing balance does not automatically indicate strong cash flow or strong returns. It can reflect years of profitable operations with limited shareholder distributions. For performance analysis, pair it with measures such as Bizverra’s return on equity guide.
What Does a Negative Balance Mean?
A deficit means cumulative losses and distributions have exceeded accumulated profits. It does not automatically mean the corporation is insolvent or out of cash. Lenders and owners will still want to understand the causes and trend.
Look first at recurring operating losses, large dividends, and significant accounting adjustments. Then compare the result with debt levels, liquidity, and recent profit trends. One equity figure rarely explains the full condition of a business.
A temporary deficit may follow a difficult expansion year or a major restructuring. A persistent deficit can point to deeper profitability or distribution problems. The direction of travel often matters as much as the single closing figure.
How to Prepare the Report Step by Step
Use a consistent closing process before building the report. Each number should trace back to the ledger or an approved corporate record. A simple five-step sequence keeps the reconciliation clear.
- Confirm the opening balance. Use the prior reporting period’s verified closing figure.
- Bring in net income or loss. Take the final amount from the current income statement.
- Record dividends declared. Use approved corporate records for the period.
- Add valid adjustments separately. Do not hide corrections inside current profit.
- Calculate and reconcile the closing balance. Match it with the balance sheet and applicable GIFI reporting.
Preparation becomes easier when the bookkeeping is already reconciled. Close bank accounts, receivables, payables, and major accruals before relying on final profit. Then verify that the ending equity figure agrees across every statement and tax schedule.
Pay special attention to dividend timing. CRA GIFI code 3700 refers to dividends declared, not merely cash paid during the period. Your corporate records should support both the declaration date and amount.
Common Errors to Avoid
Most mistakes are reconciliation errors rather than formula errors. They usually begin with a wrong opening balance or an unposted year-end entry. A structured review can catch them before tax filing or external reporting.
- Starting with last year’s opening amount instead of its closing amount.
- Treating shareholder dividends as an operating expense.
- Using cash withdrawals without checking how they were legally recorded.
- Ignoring prior-period adjustments that changed the opening balance.
- Failing to match the closing amount with shareholders’ equity.
- Mixing sole-proprietor drawings with corporate dividend accounting.
- Using draft net income before final year-end entries are posted.
Frequently Asked Questions
Is a Statement of Retained Earnings Required in Canada?
For corporations governed by the federal CBCA, section 72 of the regulations requires equity-change reporting within the referenced annual financial statements. It allows either a changes-in-equity statement or the narrower reporting format. Provincial rules and accounting frameworks can differ, so confirm which requirements govern your corporation.
Is it the same as a statement of changes in equity?
The reports overlap, but a broader equity statement can include more components. It may show share capital, contributed surplus, and other comprehensive income alongside accumulated profit. BDC also notes that IFRS reporting uses a statement of changes in shareholders’ equity.
Where does the ending balance appear?
The closing amount appears within shareholders’ equity on the balance sheet. CRA also expects the ending GIFI amount to agree with the corresponding equity balance. A mismatch usually signals an entry, mapping, or adjustment problem.
Can a profitable company finish with a lower accumulated balance?
Yes, because dividends can exceed the year’s net income. That situation reduces accumulated equity despite a profitable reporting period. Prior-period or other equity adjustments can also reduce the closing figure.
Does a sole proprietor use this report?
Sole proprietors usually focus on owner’s capital and drawings instead. Corporate accumulated-profit reporting is tied to shareholder equity and dividend decisions. A sole proprietor should follow the reporting format that applies to their business structure.
Your Next Step
Start with last year’s closing equity balance and your current income statement. Reconcile dividends and adjustments, then confirm the closing figure on the balance sheet. If the numbers disagree, fix the ledger before using them for tax or financing decisions.