
A profitable year does not tell you how much profit a corporation has kept over time. Retained earnings track accumulated profits after accounting for losses and shareholder distributions. For Canadian corporations, this figure forms part of shareholders’ equity on the balance sheet.
Put simply, the balance shows how much accumulated profit remains within the corporation from an accounting perspective. It can rise through net income and fall through losses or dividends. Don’t confuse it with the amount in your business bank account.
| Key point | What it means |
|---|---|
| Account type | Shareholders’ equity |
| Main formula | Opening balance + net income − dividends = closing balance |
| Financial statement | Balance sheet or statement of changes in equity |
| Positive balance | Accumulated profits exceed relevant reductions |
| Negative balance | An accumulated deficit exists |
| CRA reporting | GIFI includes specific codes for corporate balances and changes |
| Cash balance? | No, the figure does not equal available cash |
What Are Retained Earnings?
Retained earnings are accumulated corporate profits not distributed to shareholders. The balance carries forward from one accounting period to the next. Losses and certain adjustments can also reduce it.
The account therefore provides a longer-term view than annual net income. Net income measures profit or loss during one reporting period. The accumulated balance reflects results carried across multiple periods.
For example, suppose a corporation earns $80,000 after tax during its first year. It declares $20,000 in dividends to shareholders. Its closing accumulated profit would be $60,000, assuming no other relevant adjustments.
That amount appears within shareholders’ equity rather than as an asset. It does not mean the corporation has $60,000 of cash available. The money may already be tied up in inventory, equipment, receivables, debt repayment, or other business needs.
Retained Earnings Formula Explained
The basic formula is straightforward:
Closing balance = Opening balance + Net income − Dividends
The opening amount normally comes from the previous accounting period’s closing balance. Current net income then increases the account, while a net loss reduces it. Dividends declared to shareholders generally reduce the balance.
Consider a Canadian corporation starting the year with an accumulated balance of $120,000. It earns $55,000 after tax and declares $15,000 of dividends. Its year-end calculation would look like this:
| Calculation | Amount |
|---|---|
| Opening balance | $120,000 |
| Add: net income | $55,000 |
| Less: dividends | ($15,000) |
| Closing balance | $160,000 |
This example also shows why annual profit and accumulated profit are different. The company earned $55,000 during the current year. Yet its closing accumulated balance reaches $160,000 because earlier results carry forward.
Where Does the Balance Appear?
The accumulated balance normally appears in the shareholders’ equity section of a corporation’s balance sheet. Share capital and other equity accounts may appear nearby. Together, these figures contribute to total shareholders’ equity.
The income statement has a different purpose. It reports revenue, expenses, and net income for a defined period. Bizverra’s income statement example explains how those figures move from revenue toward the final net income figure.
Net income then feeds into the corporation’s equity accounts at period end. This connection links the income statement to the balance sheet. Bizverra’s general ledger example also shows an accumulated profit account within a Canadian chart of accounts.
How Canadian Corporations Report the Balance to the CRA
Canadian corporations commonly submit financial statement information with their T2 returns using the General Index of Financial Information. The CRA assigns standardized GIFI codes to financial statement items. These codes allow companies to report financial information consistently.
CRA guidance on the GIFI identifies code 3600 for the accumulated profit or deficit account. A more detailed reconciliation can use code 3660 for the starting balance. Code 3680 covers net income or loss, while code 3700 covers dividends declared.
When you report a detailed reconciliation, code 3849 represents the ending balance. The CRA states that this amount should agree with code 3600. This reconciliation helps connect opening equity, current results, distributions, and closing equity.
These reporting rules make accurate year-end bookkeeping important. An incorrect opening amount can carry an error into later periods. Businesses should reconcile the opening figure with the previous year’s finalized financial statements.
Retained Profit Is Not the Same as Cash
This distinction often confuses business owners. A corporation can report a substantial accumulated profit while holding much less cash. Accounting profit and available cash measure different things.
Imagine a company has accumulated $200,000 of profit over several years. It then spends $100,000 on equipment and uses another $50,000 for working capital. Those transactions can change the asset mix without automatically eliminating the accumulated profit account.
Accounts receivable create another common difference. Revenue can contribute to profit before a customer has paid the related invoice. A company can therefore report healthy accounting results while experiencing tight cash flow.
Business owners should review the balance sheet and cash flow information together. No single equity account shows whether a company can comfortably meet upcoming payments. Liquidity requires separate attention to cash, receivables, payables, debt, and other short-term obligations.
What Does a Negative Balance Mean?
A negative accumulated balance is commonly described as an accumulated deficit. It means cumulative losses and relevant distributions have exceeded accumulated profits. This situation can develop over several reporting periods.
A negative figure does not automatically mean a company is insolvent. A young corporation may record early losses while building its customer base. An established business may also be recovering from earlier unprofitable years.
The direction of the balance matters as much as its cause. A company moving from a $100,000 deficit to a $30,000 deficit may be improving. A previously profitable company moving rapidly into a deficit deserves closer examination.
Look beyond the single number before drawing conclusions. Review recent profitability, cash flow, debt, shareholder distributions, and working capital. These figures provide context that an accumulated deficit cannot provide on its own.
Retained Profit Versus Net Income
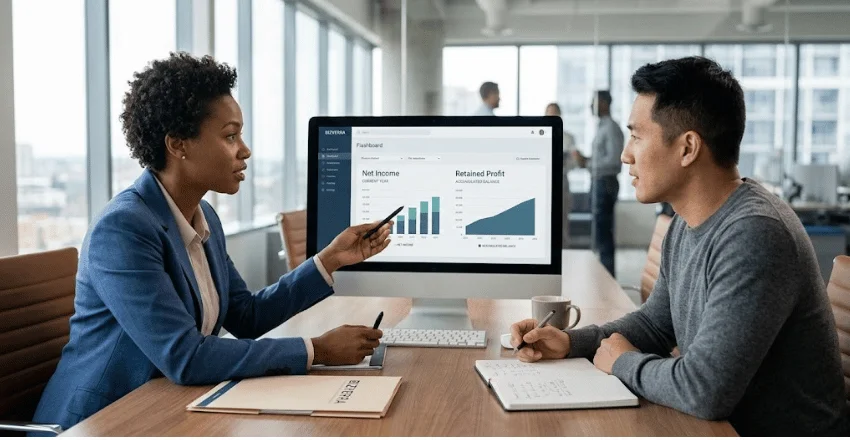
Net income measures financial performance during a particular accounting period. The accumulated profit account carries results from earlier periods forward. That timing difference separates the two measures.
Suppose a corporation begins the year with $90,000 accumulated from previous periods. It earns $25,000 during the current year and declares no dividends. Net income is $25,000, while the closing accumulated balance becomes $115,000.
The distinction matters when comparing companies or reviewing your own financial statements. A strong current year may follow several weak years. Conversely, one difficult year can reduce a large balance built through years of profitable operations.
Your fiscal year also determines the period covered by the current net income figure. Bizverra’s guide to choosing a fiscal year explains reporting periods for Canadian businesses. The closing equity balance then becomes the opening figure for the next period. There is more on this in how Canadian fiscal years work.
How Dividends Affect the Account
Dividends are distributions to shareholders, not normal operating expenses. They therefore do not reduce operating profit like wages, rent, or advertising costs. Instead, declared dividends affect equity after profit has been determined.
For Canadian corporations, dividend taxation involves rules beyond basic financial accounting. Taxable dividends may be eligible or other than eligible, depending on applicable tax rules. Private corporations can also encounter accounts such as GRIP, LRIP, RDTOH, and the capital dividend account.
That means an accounting balance alone does not determine the tax treatment of a proposed dividend. Corporate tax attributes and legal requirements may also matter. Owners should confirm significant distributions with their accountant or tax adviser before declaring them.
The same caution applies when comparing salary and dividends for owner compensation. Each method can affect corporate and personal taxation differently. The accumulated equity figure is only one part of that decision.
What Can a Corporation Do With Accumulated Profits?
Keeping profits inside a corporation can support future business activity. Companies may use them to finance equipment, inventory, marketing, hiring, or debt reduction. They may also preserve financial capacity for slower periods.
The accounting balance itself is not a dedicated pool of money. Management decides how to deploy corporate assets after profits are earned. Those decisions can change cash, equipment, inventory, receivables, or liabilities without matching the equity balance dollar for dollar.
A growing balance can indicate that a company has generated profits and kept part of them inside the business. Yet a larger number is not automatically better. Owners should consider whether the corporation is using retained capital productively.
For operating analysis, expenses deserve the same attention as equity. Bizverra’s SG&A guide explains how common overhead costs affect operating profit. Controlling those costs can improve net income, which can eventually strengthen accumulated equity.
How to Review the Number Each Year
Start by comparing the opening figure with last year’s finalized closing balance. They should normally connect unless an adjustment explains the difference. Investigate unexplained changes before relying on current statements.
Next, trace current net income from the income statement into the equity reconciliation. Confirm any dividends or other relevant adjustments recorded during the period. Then verify that the closing amount agrees with the balance sheet.
Finally, compare the accounting result with cash flow and business plans. Ask whether the company can fund upcoming obligations and planned investments. This approach gives the equity figure practical meaning rather than treating it as an isolated accounting number.
Frequently Asked Questions
Are retained earnings an asset?
No. Retained earnings form part of shareholders’ equity rather than assets. Assets include cash, receivables, inventory, and equipment.
The distinction matters because accumulated profits can be invested in those assets. A large equity balance therefore does not guarantee a matching cash balance. Always check the asset side of the balance sheet separately.
Can the balance be negative?
Yes. A negative balance is generally called an accumulated deficit. It can result from cumulative losses, distributions, or a combination of both.
Review a deficit in context rather than judge it alone. Current profitability, liquidity, debt, and the company’s stage of development can change its significance. Several years of movement often tell more than one year-end figure.
Is it the same as net income?
No. Net income measures profit or loss for one reporting period. The accumulated account carries prior results forward and reflects relevant distributions.
A profitable company can therefore begin a year with a negative accumulated balance. Current profit may reduce that deficit without immediately turning the balance positive. The two measures answer different financial questions.
Does the balance equal cash available for dividends?
No. Accounting equity does not tell you how much cash is available for distribution. Profits may have been invested in inventory, receivables, equipment, or other assets.
Canadian corporations must also consider applicable corporate and tax rules before paying dividends. Available cash, solvency, and corporate tax attributes may all require review. An accountant can assess the specific circumstances before a material distribution.
Make the Number Useful, Not Merely Accurate
Accumulated corporate profit becomes useful when you connect it with profitability, cash flow, distributions, and business investment. The balance shows part of a corporation’s financial history. It does not explain that history on its own.
Review the figure with your income statement, balance sheet, and cash flow information each reporting period. Reconcile unexplained changes before making financing or distribution decisions. Good bookkeeping makes that review faster and reduces year-end surprises.
For Canadian corporations, accurate records also support consistent GIFI reporting with the T2 return. Bizverra’s accounting guides can help you understand how the general ledger and the statement of retained earnings connect. For tax-sensitive decisions, confirm the treatment with a qualified Canadian accountant or tax professional.